Buying a home in Singapore might seem scary, but with some tips, you can feel more at ease. It’s important to know about the various types of homes, who can buy them, and what costs are involved. This guide will give you the key things to remember when looking for a home in Singapore.
Key Takeaways
- Understand the different types of properties available in Singapore, including HDB flats, private condominiums, and landed homes.
- Familiarize yourself with the eligibility criteria for various property types to ensure you meet the necessary requirements.
- Develop a comprehensive home buying budget that considers immediate and future costs, as well as government subsidies and grants.
- Evaluate location factors, such as proximity to amenities, transportation, and job hubs, to find the perfect neighborhood for your needs.
- Explore financing options, including HDB loans and bank loans, and compare interest rates, loan amounts, and repayment flexibility.
Navigating Singapore’s Property Landscape
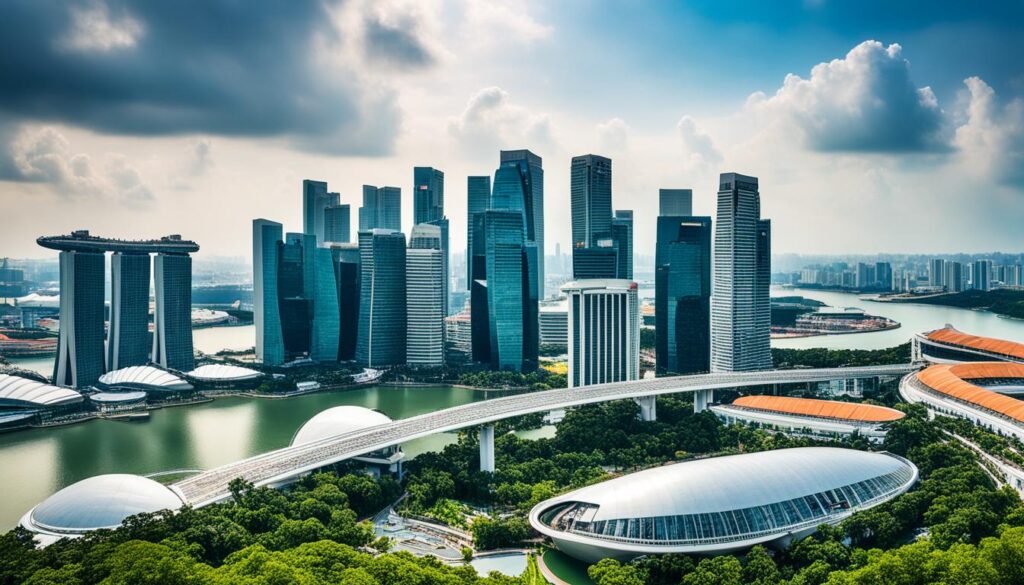
The Singapore property market has a lot to offer. It includes public housing by the Housing and Development Board (HDB) and private condominiums. This range of options caters to different needs and budgets.
Types of Properties in Singapore
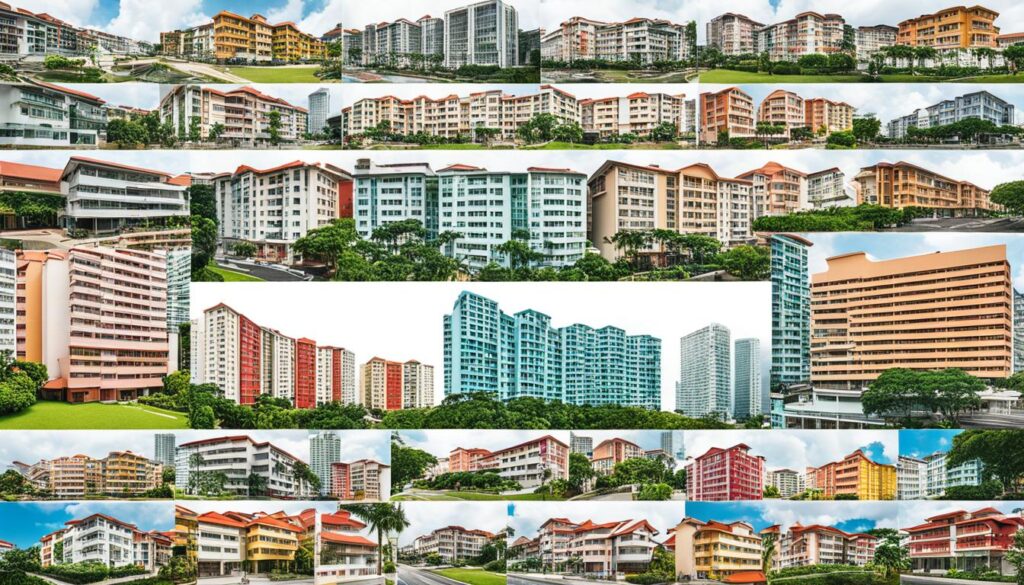
HDB flats are the most common type of housing. They offer sizes from studios to 5-room units. Also, you can find resale HDB flats and private condos for more amenities. ECs are a mix, cheaper initially but with selling restrictions.
Eligibility Criteria for Different Property Types
To buy different properties, you need to meet certain criteria. This includes your citizenship, income, and the size of your household. For example, HDB flats have income limits and ownership rules. Knowing these rules helps buyers understand their options in the Real Estate Singapore market.
Planning Your Home Buying Budget
Purchasing a property in Singapore needs careful financial planning. If you’re thinking about buying a house, it’s important to look at your current and future costs. This means looking at things like the downpayment, which could be as low as 20% for an HDB loan. This can be paid using money from your CPF Ordinary Account (OA). If you get a bank loan, the downpayment is usually 25%, with 5% paid in cash and the other 20% from cash or CPF OA.
Immediate and Future Costs
Aside from the downpayment, there are other costs to think about. Things like stamp duties, legal fees, and renovation fees can increase your overall budget. It’s crucial to also remember your monthly mortgage payments. The amount you pay monthly depends on the Property Prices Singapore, the loan you get, and interest rates. Knowing and planning for these costs helps you get ready for owning a Residential Properties Singapore.
Government Subsidies and Grants
There’s good news from the Singapore government. They provide many grants and subsidies to help new Property Developers Singapore and Property Agents Singapore. Programs like the Enhanced CPF Housing Grant and the Proximity Housing Grant can really help. They aim to make homes in Singapore more affordable and easier to get for its citizens.
Location Considerations for Your New Home
Choosing the right location for your new home is very important. If you want a Residential Properties Singapore, luxury homes in Singapore, or a commercial property, location matters a lot. It affects your daily life, your travel time, and the property’s future value.
Be sure to think about how close the house is to your work. Living closer to your job makes you save time and money. It’s also less stressful than driving long distances through Singapore’s hectic traffic. Homes near places like MRT stations or bus stops make it easy to get to where you need to go in the city.
It’s also key to check what’s around the area. Living in a place with lots of facilities may cost more. But, it often means you’ll have easy access to shopping, healthcare, and fun. Places that are still growing might be cheaper. However, they might not have as many nearby services.
If living close to your family is important, it could mean a benefit. You might be able to get a special grant from the government. This grant encourages families to live near their older family members. It helps build stronger family connections.
Deciding on a home means balancing how easy it is to get around with how much it costs. Looking at these details closely will help you choose well. Make sure the home you pick fits your budget and meets your goals, whether it’s Luxury Homes Singapore or Commercial Properties Singapore.
Singapore Property: Additional Costs to Budget For
Buying a property in Singapore is exciting, but it comes with many extra costs. These include things besides the downpayment and monthly mortgage. To dive into the real estate market here, you need to think about these extra expenses.
Fees and Charges for HDB Flats
HDB flats in Singapore have their own set of extra costs. For example, buyers must pay for a property valuation report and buyer stamp duty. Don’t forget about monthly property taxes and insurance costs too. All these add-ons are key to know about before you buy.
Costs for Resale Flats
Resale flats in Singapore’s property market can cost even more. Buyers might pay property agent commissions and fees for the Option to Purchase (OTP). Renovation costs could be higher too. Stamp duty fees for resale flats are usually higher than for new ones. These all stack up on top of the initial cost.
There are ongoing costs to prepare for as well. These include utilities, groceries, and maintenance for your new place. This is true for everyone owning a property in Singapore, at least in the beginning.
Thinking about all these extra costs is essential. It’s smart planning for anyone looking to invest in the Singapore real estate market. Knowing all costs helps buyers make choices that fit their financial goals.
HDB Loans vs Bank Loans: Which is Better?
In Singapore, property buyers can choose between HDB and bank loans. Each type has its own features that will affect your purchase. It’s important to understand these differences to meet your financial needs.
Interest Rates and Loan Amounts
HDB loans come with a fixed interest rate of 2.6% yearly. This rate doesn’t change over the loan term. You’ll know exactly what to pay each month for your Property Developers Singapore and Property Agents Singapore deal. You can borrow up to 80% of the property’s price. This allows you to use less cash and get into Residential Properties Singapore more easily.
Bank loans, however, might have rates that change. With fixed rates, you won’t worry about sudden hikes in interest. But you might end up paying more if the rates float with the market. Banks usually lend up to 75% of the property price. So, you’ll need a bigger downpayment.
Repayment Flexibility and Penalties
HDB loans let you use your CPF savings for the full downpayment. This lowers how much cash you need on hand. But, if you pay off the loan early or refinance, you might face extra charges.
Bank loans can offer more choice in how you can pay back. Yet, you must have at least 5% of the property’s value in cash. This is besides using any CPF funds.
Choosing between HDB and bank loans means looking at a few key things. Consider interest rates, how much you can borrow, how flexible you need to be with payments, and the possible costs of paying back early. This will help you pick what works best for your situation, whether it’s for Property Prices Singapore or finding the right Residential Properties Singapore.
Preparing Your Finances for Home Ownership
Buying a home, whether it’s a villa in Singapore or a space for your business, means careful money planning. It’s vital to look closely at your money situation. This includes checking your earnings, what you already spend, any debts, and your credit score. Knowing this info helps you see what you can actually pay. It also guides you to the right loan choice.
Assessing Your Financial Health
Start by looking at how much money you make each month. This can be from your job, extra earnings, or rent from a Property Investment Singapore. Then, list all your regular costs, like bills and loans. Figuring this out shows how much you can put towards a loan each month. Don’t forget to check your credit score. A good score helps you get a better deal on a loan for a Luxury Homes Singapore.
Saving for the Down Payment
Having a big down payment saves you money in the long run. It can cut down your monthly loan and lower what you pay in interest over time. Try saving a little every month, paying off high debts, or living a bit more frugally. This way, you show you’re responsible and serious. It makes you more appealing to Property Developers Singapore.
Getting ready to buy a home takes effort and smart money moves. By checking your finances and saving ahead, buying a Property Investment Singapore becomes a more certain prospect, with better loan deals. Whether you’re after a dream home or a Commercial Properties Singapore, good planning sets you up for success.
Comparing Home Loan Options in Singapore
When you’re buying a new home in Singapore, you’ll have two top loan types to pick from: HDB loans or bank loans. Knowing what sets these choices apart is key to making a smart decision. It should fit your money situation and what you plan for the future.
HDB loans from the Housing Development Board come with a set 2.6% interest rate each year. They need a smaller downpayment, which is great for those buying their first home in Singapore. Bank loans, from different finance groups, can cover HDB or private homes. But, they ask for a bigger 25% downpayment.
Bank loans might have lower interest rates, but they also add more fees and could charge for paying early. HDB loans, on the other hand, are easier to get and manage financially. This gives more choices and makes owning a home in Singapore more doable.
Look closely at interest rates, how much you can borrow, how flexible you can be with payments, and extra costs for each loan type. By understanding these details about HDB and bank loans, you can choose what’s best for you. This way, your path to buying a home will be smoother.
The Home Buying Process in Singapore
Finding the right property in Singapore is a step-by-step process. First, you need to check if you can buy different types of properties. This depends on your citizenship, marriage, age, and income. This step helps follow rules and shortlist your search.
After checking your eligibility, it’s time to set a budget. This means looking at costs now and in the future, including your mortgage. It’s key to know what you can afford when looking at property in Singapore. This applies whether you’re considering Property Investment Singapore or dreaming of Luxury Homes Singapore. It’s also important for Commercial Properties Singapore or dealing with Property Developers Singapore.
With your budget in place, start looking for your dream home. It’s important to compare different home loans to get the best deal. When you find a property you like, you have to put down a payment. This means you can reserve it and move to buy with an Option to Purchase (OTP). The last steps include finalizing your home loan, buying the property, and sorting out the paperwork.