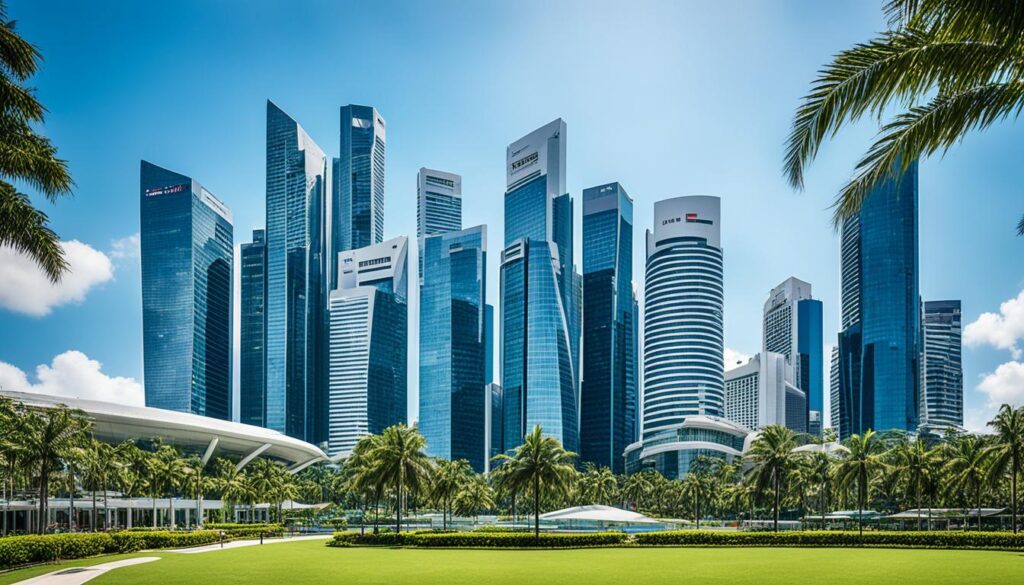
Imagine the sense of fulfillment that washes over you as you turn the key in the lock of a property that’s truly yours. In the bustling heart of Asia, Singapore’s blend of modern urban charm and lush green landscapes creates a unique canvas where dreams of homeownership come to life. For many, buying property in Singapore isn’t just a transaction; it’s a pivotal life milestone, marked by the rigorous planning and the satisfaction of establishing roots in one of the world’s most vibrant cities.
The journey to owning a piece of the Singapore property market can be complex, but the allure of stability and the pride of investment keep the vision alive. Whether you’re seeking an HDB flat to start your family story or a luxurious private property as your urban sanctuary, this property buying guide Singapore is designed to navigate you through cascading choices and legal intricacies, shedding light on the path to your real estate aspirations.
As you embark on the quest for your perfect home or investment, let this guide illuminate the nuances of buying property in Singapore, tailored to inform your decisions with clarity and confidence.
Key Takeaways
- Discover the diversity of the Singapore property market, including HDB flats, private properties, and Executive Condominiums (ECs).
- Unveil the prerequisites of homeownership in Singapore through a comprehensive eligibility breakdown for individuals and families.
- Gain insights into the impact of government grants and subsidies on making homeownership accessible in Singapore.
- Delve into the financial considerations crucial to acquiring property, from stamp duties to the Loan-To-Value (LTV) limit.
- Understand the opportunities and restrictions for both Singapore residents and international investors wishing to purchase property.
Understanding the Singapore Property Landscape
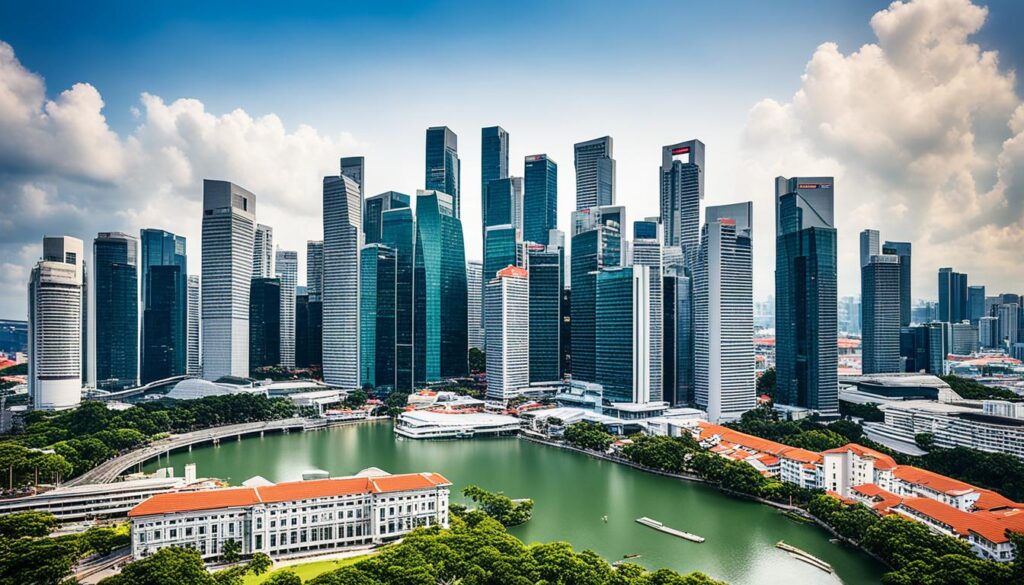
Embarking on the journey of investing in Singapore real estate requires familiarizing oneself with the diverse types of properties and navigating through the intricacies of demographic eligibility and stringent property cooling measures. This multi-faceted market presents numerous opportunities and considerations for both locals and international investors.
Types of Available Properties in Singapore
The Singapore property market is known for its extensive range of options, appealing to a variety of preferences and investment strategies. The types of properties in Singapore include:
- HDB Flats: These are affordable, government-subsidized housing units, designed for Singapore Citizens and Permanent Residents.
- Private Properties: Encompassing both condominiums and landed homes, these properties offer enhanced privacy and facilities, accessible to both locals and foreigners.
- Executive Condominiums (ECs): Bridging the gap between HDB flats and private condominiums, ECs are a lucrative option for eligible buyers seeking an upscale lifestyle at a subsidised cost.
Demographic Eligibility: Who Can Buy?
Understanding how to buy property in Singapore is crucial, as eligibility can vary vastly across different demographic segments:
- Singapore Citizens: Enjoy the privilege of purchasing any property type without restrictions.
- Permanent Residents: Able to acquire HDB flats and private properties, with certain limitations for singles.
- Singles Aged 35 and Above: Entitled to purchase resale HDB flats and private properties.
- Families and Divorcees: Subject to various conditions, they enjoy a broader scope in the HDB market.
The Impact of Recent Property Cooling Measures
Investing in Singapore real estate now comes with a heightened sense of responsibility due to recently implemented property cooling measures. These measures are designed to maintain a stable and sustainable property market:
- Adjusted Loan-To-Value Limits: Home loan limits have been tightened to encourage prudent borrowing and financial foresight.
- Additional Buyer’s Stamp Duty: Elevated rates have been introduced to dissuade speculative investing and ensure long-term commitment to property purchases.
- Tighter Restrictions for PRs: To prioritize housing availability for citizens, Permanent Residents now face more stringent measures when purchasing their first property.
Eligibility Criteria for Purchasing Property as a Singaporean
Understanding the eligibility criteria for buying property in Singapore is the cornerstone of the property buying process for locals. The criteria set by the Housing & Development Board (HDB) define whether a citizen is able to apply for and purchase an HDB flat, which is a key route to homeownership in Singapore.
At the outset, an individual must meet the basic age requirement, which is usually a minimum of 21 years. But this is just the beginning—eligibility expands into various categories based on the applicant’s family status and the type of property they intend to buy.
- Families and married couples have the privilege of choosing from a broad range of HDB flats.
- Divorcees are granted specific concessions and may be eligible to purchase HDB properties, subject to the fulfillment of certain conditions set by HDB.
- Single Singaporeans who are 35 years old and above may apply to buy resale HDB flats, albeit with limitations on size and location, specifically being restricted to 2-room flats in non-mature estates.
For those applying under the Joint Singles Scheme to co-own a resale HDB flat, the ‘essential occupier’ criteria is worth noting. This category is reserved for those individuals who form part of the family nucleus, either as fellow citizens or Permanent Residents.
Owning an HDB flat is not only about eligibility but also adhering to obligations. For instance, there’s a requirement to fulfill the Minimum Occupancy Period before the flat can be sold or rented out. Additionally, HDB flat owners are usually subject to a period during which they are not eligible to purchase private properties.
Prospective buyers are encouraged to thoroughly review HDB’s eligibility conditions, as they form the foundational steps in the property buying process in Singapore, ensuring a smooth journey towards homeownership for citizens across different walks of life.
Options for Foreigners Buying Property in Singapore
Delving into the Singapore property market for expats unveils a range of investment possibilities. Despite certain restrictions, the nation’s prosperous economy and robust legal framework foster an environment where property options for foreigners in Singapore remain extensive and varied. From sleek high-rise condominiums to luxurious apartments, the market is ripe with opportunities for both living and investment purposes. However, it is crucial for foreign nationals to navigate the regulations that govern the acquisition of different types of properties.
Gaining Approval for Landed Property
While foreign investors are free to purchase condominium units and apartments, the same does not hold true for landed properties such as terraced houses and bungalows. These types of properties are highly coveted and their ownership is tightly regulated to preserve local interests. Expats keen on these prestigious properties must seek approval from the Singapore Land Authority, adhering to specific criteria and regulations set forth under the Residential Property Act. This process ensures a careful evaluation of foreign investments in Singapore’s finite landed residential spaces.
Executive Condominiums (ECs): Understanding the 10-Year Rule
Executive Condominiums (ECs) offer a hybrid form of housing, combining the features of public and private housing. While initially these complexes are catered towards Singaporeans, a distinctive rule opens the door to expatriates. Following a 10-year maturation period from their initial development, ECs become wholly privatized, shedding their subsidization and public ownership constructs. At this juncture, they join the pool of property options accessible to foreigners, allowing expat investors to tap into ECs for foreigners that often reside in attractive locations and boast amenities comparable to private condominiums.
Foreign purchasers thus play a significant role in the overall landscape of the Singapore property market for expats. Notwithstanding the restrictions on landed property and EC ownership, Singapore’s offerings for expatriates remain robust, securing its status as a global hub for property investment. As the market continues to evolve, so too does the potential for novel real estate ventures and opportunities within this dynamic region.
The Financial Aspect of Buying Property in Singapore
Understanding the financial commitments involved in property ownership is imperative for any aspiring homeowner in Singapore. Aside from the purchase price, there are several additional costs that must be factored into your budgeting plans. A clear perspective on these monetary obligations aids in assembling a more complete picture of the property buying process in Singapore. Below, we delve into the average expenses, hidden costs, and the loan options available to buyers in Singapore’s dynamic real estate market.
Assessing the Average Property Costs
The average property costs in Singapore might vary widely depending on the property type and location, but a common thread across all purchases are the associated fees. For those interested in HDB flats, market rates are influenced by a variety of factors including the flat’s size, condition, and estate maturity. Private properties, meanwhile, can command significantly higher prices, thus it is crucial for buyers to conduct thorough market research and be informed about the ongoing rates to make prudent investment choices.
Legal Fees and Additional Ownership Costs
When buying property, be prepared for additional expenses such as legal fees, stamp duties, and maintenance costs. Legal fees cover the conveyancing process, while stamp duties are tax payments made to the government. Maintenance expenses and home insurance also contribute to the periodic financial outlays that come with property ownership. Prospective buyers should not overlook these expenses, as they are integral components of the total cost of ownership and can impact overall affordability.
Exploring Loan Options: HDB Concessionary Loan and Beyond
For financing, an HDB Concessionary Loan may be available for eligible buyers of HDB flats, potentially covering up to 80% of the valuation limit with an LTV ratio. Private properties typically necessitate bank loans, with LTV limits averaging 75%. Moreover, leveraging Central Provident Fund (CPF) savings is a common strategy to offset purchasing costs, subject to specific limitations. Buyers should investigate these and other loan options thoroughly to secure the best possible terms, ensuring their property investment is financially sustainable. Heeding these tips for buying property in Singapore could steer you toward making choices that dovetail with your fiscal plans and long-term objectives.